
Article summary
A weekly cash-flow forecast estimates when money will enter and leave a business. This fictional four-week example calculates each closing cash balance, moves a late customer receipt to a later week and checks forecast against actual cash. It is a simplified learning exercise, not a forecast for a real company or a financing recommendation.
Start with cash dates rather than invoice dates
Fictional Cedar Components starts Week 1 with INR 100 thousand in confirmed cash. Its finance team lists expected customer collections and planned supplier, payroll and other payments by the week cash is expected to move. The invoice date alone is not a reliable cash date: a customer may pay late and a bill can be due in a different week from when it was entered. Sources for a real forecast might include a reconciled bank balance, receivables, payables, payroll dates and approved payment schedules. Record each assumption and its owner so a later forecast change can be explained.
Build the four-week base forecast
| Week | Opening cash | Receipts | Payments | Net movement | Closing cash |
|---|---|---|---|---|---|
| 1 | 100 | 80 | 120 | −40 | 60 |
| 2 | 60 | 70 | 70 | 0 | 60 |
| 3 | 60 | 90 | 95 | −5 | 55 |
| 4 | 55 | 100 | 75 | +25 | 80 |
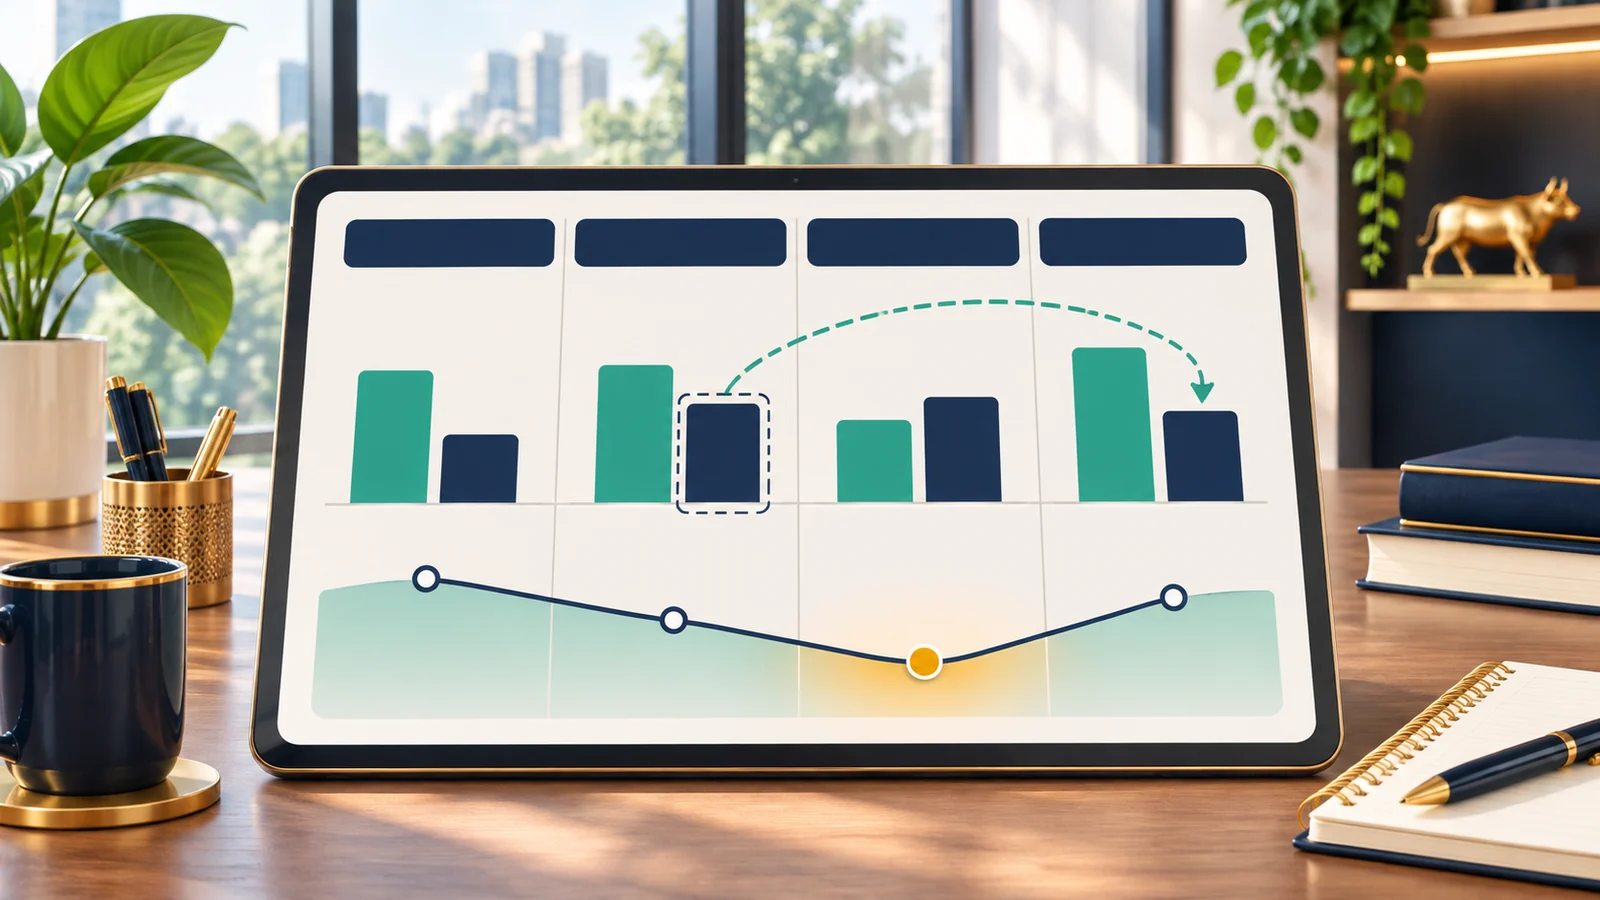
For Week 1, INR 100 thousand opening cash plus INR 80 thousand receipts minus INR 120 thousand payments leaves INR 60 thousand. Week 2 opens at 60, not at the original 100. The same roll-forward gives closing cash of 60, 55 and 80 in Weeks 2, 3 and 4. The base plan never falls below INR 55 thousand. It does not prove each receipt will arrive: it shows what follows if the stated timing assumptions hold.
Test a delayed customer receipt
Assume INR 40 thousand of Week 2's expected receipts is now likely to arrive in Week 4. Keep every payment unchanged and assume Week 1 happened exactly as forecast. Move that 40 from Week 2 to Week 4; do not count it in both weeks. This scenario changes the low point even though the four-week ending cash is unchanged.
| Week | Opening cash | Revised receipts | Payments | Closing cash | Change from base close |
|---|---|---|---|---|---|
| 2 | 60 | 30 | 70 | 20 | −40 |
| 3 | 20 | 90 | 95 | 15 | −40 |
| 4 | 15 | 140 | 75 | 80 | 0 |
Week 2 now closes at 60 + 30 − 70 = INR 20 thousand; Week 3 closes at 20 + 90 − 95 = INR 15 thousand. If the team had set a fictional INR 25 thousand minimum operating buffer, Weeks 2 and 3 would be below it. Week 4 recovers to 15 + 140 − 75 = INR 80 thousand only if the delayed payment actually arrives then. The appropriate next step is to verify the payment expectation and escalate the potential shortfall under the organisation's process, not to assume an overdraft or defer an authorised payment without approval.
Compare forecast with actual cash
Now treat Week 1 as closed. Suppose actual receipts were INR 75 thousand, rather than 80, and actual payments were INR 125 thousand, rather than 120. Actual closing cash is 100 + 75 − 125 = INR 50 thousand, which is INR 10 thousand below the Week 1 forecast close of 60. The variance consists of INR 5 thousand less received and INR 5 thousand more paid. The next forecast must start Week 2 from the reconciled actual INR 50 thousand, then apply newly verified timing assumptions. It must not keep the old Week 2 opening 60 just because that was in the first version.
Avoid three common forecast errors
- Do not treat a recorded sale or issued invoice as collected cash. Use a documented expected receipt date and update it when evidence changes.
- Do not add a delayed receipt to a later week without removing it from the original week. The four-week total would be overstated.
- Do not mix a prior forecast with actual cash after a week closes. Reconcile the actual balance and explain the variance before rolling forward.
This direct short-term forecast differs from a cash-flow statement, which reports cash movements over a completed accounting period. It also differs from a three-statement model, which links profit, balance-sheet changes and cash-flow projections. The weekly exercise focuses on timing and control of expected receipts and payments. More detailed business forecasts can include taxes, financing, currencies and multiple bank accounts; none are modelled here.
Source and learning scope
Microsoft Learn's cash-flow overview describes forecasts using expected cash receipts, disbursements and net cash movement. The week-by-week figures, delayed receipt, buffer and variance in this article were invented for practice and checked independently. The source describes a software workflow; this article does not claim Centaur teaches that product or that this simple grid is a full treasury model.