
Finance Operations
Payment Reconciliation: Process, Breaks and Controls
See how teams match bank, gateway, settlement and ledger records, classify payment breaks, document evidence and escalate unresolved exceptions.
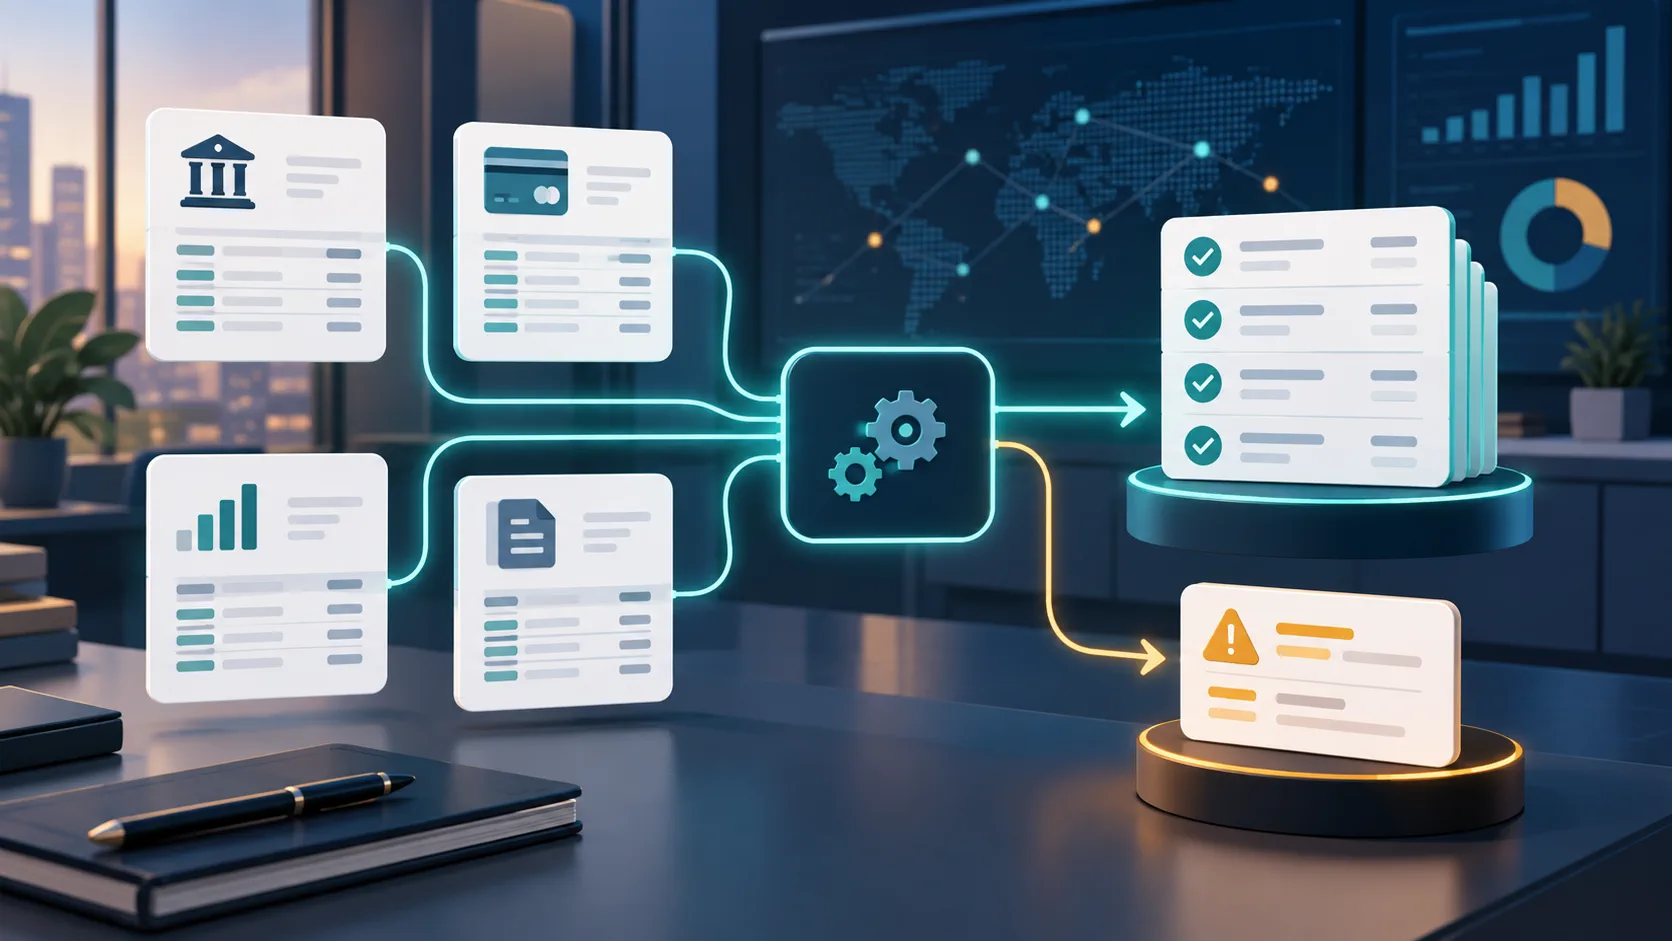
Payment reconciliation compares records from a payment journey and explains differences without forcing the systems to match. A team may compare a payment gateway report, bank statement, settlement file, customer order and finance ledger. Each source can use different references, dates, statuses and file structures. A reliable process defines the population, protects the source files, matches controlled fields, investigates breaks and records the final action. This article describes a general operations workflow; payment rules and customer handling must follow the relevant provider, bank, policy and current requirements. The cases are fictional.
Why payment reconciliation is different
A payment can be initiated, authorised, processed, settled, returned or reversed across multiple systems. A successful customer-facing status may not mean the funds have reached the final ledger, and a bank credit may arrive with a reference that does not exactly match the order record. Timing, fees, partial refunds, duplicate callbacks, returns and file cut-offs can all create differences. The analyst should understand what each record means before calling it a match or break.
A six-step reconciliation process
- Define scope: date, currency, account, payment channel, settlement cycle, population and owner.
- Collect immutable or controlled copies of gateway, bank, settlement, order and ledger data with extraction timestamps.
- Standardise identifiers, dates, amounts, currency and status values while retaining the original fields.
- Match exact records first, then use approved one-to-many or tolerance rules with clear review boundaries.
- Classify breaks such as missing, duplicate, amount mismatch, timing, fee, refund, return or wrong-reference.
- Resolve, carry forward or escalate each break with evidence, owner, ageing and reviewer status.
A fictional payment break
A fictional gateway report shows a payment reference PX204 as successful for 2,500, while the bank file shows 2,475 and the finance ledger shows no posting. The analyst records all three values, checks whether the difference is an approved fee, verifies the settlement date and searches the exception or suspense queue. They do not edit the ledger to make the totals agree. If the fee and settlement are supported, the case may require separate posting and approval; if the evidence is incomplete, the item remains open for the authorised owner. The values and reference are invented.
Controls that improve payment matching
- Retain source files and record the extraction time, system and version.
- Use a controlled reference hierarchy rather than matching on amount alone.
- Separate automated matching from manual override and require a reason for the override.
- Reconcile settlement totals to the finance ledger and bank account at the agreed frequency.
- Age unresolved breaks and escalate repeated failures to the process or technology owner.
- Keep customer communication accurate; do not confirm a balance change until the authorised record is verified.
Choose matching fields deliberately
Reference is often the strongest key, but it may be absent, truncated or changed between systems. An analyst can combine reference, amount, currency, value date, account, customer or order identifier and event status according to the approved matching design. A one-to-many match needs extra care because one settlement may represent several payments. Tolerances should be documented and reviewed, not hidden in a spreadsheet formula. When a field is normalised, the original value should remain available so the reviewer can see what changed.
- Record the source and meaning of every matching field.
- Separate exact matches from probable matches and manual overrides.
- Age breaks by root cause, not only by date.
- Measure repeat failures at the source system or file level.
- Close a case only when the evidence supports the recorded outcome.
Read the core reconciliation workflow
Follow the UPI payment lifecycle
Explore digital payments operations
For interview practice, describe a break using four parts: source records, matching rule, root-cause hypothesis and next controlled action. A strong answer avoids assuming that a successful status, a bank credit or a ledger posting is sufficient on its own. Centaur Careers publishes this guide for education; it is not payment, accounting, banking or customer-specific advice.
Continue your finance career journey
Explore the learning tracks and placement support available through Centaur Careers.