
Retail Banking
UPI Payment Lifecycle: From Initiation to Settlement
Follow a UPI payment from customer initiation through authorization, routing, status updates, exception handling and reconciliation.
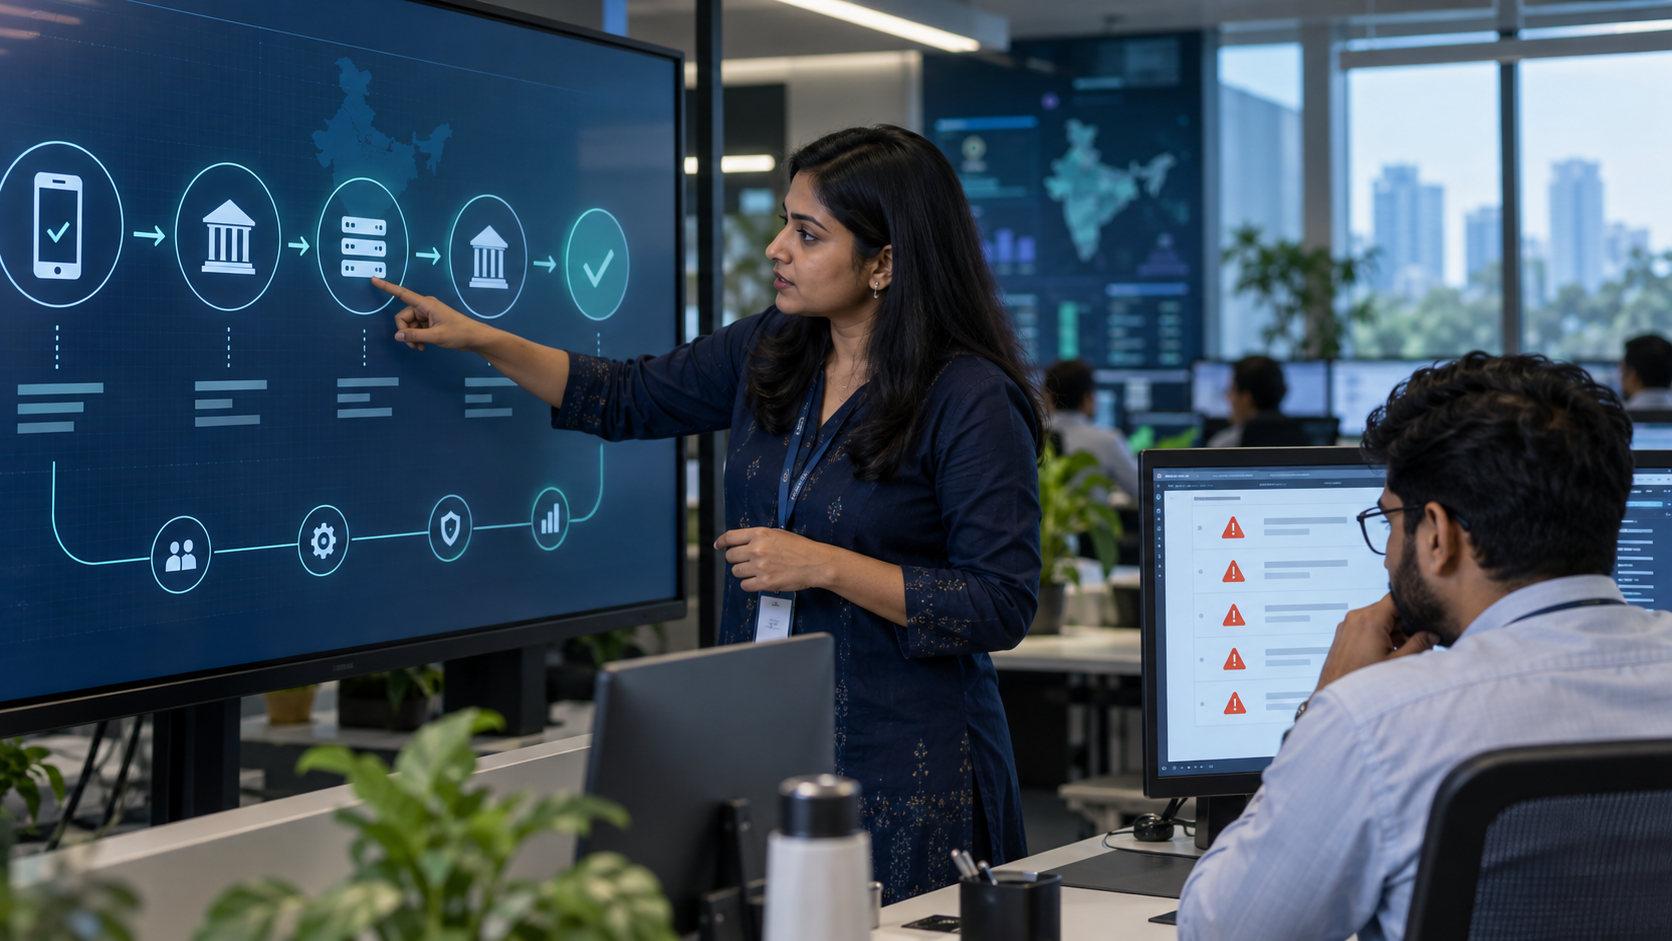
The Unified Payments Interface (UPI) is an instant payment system developed by the National Payments Corporation of India (NPCI), an RBI-regulated entity. It enables participating services to support account-to-account payments through approved apps and bank connections. The customer experience may look like one tap, but the operational journey involves instructions, authentication, participating institutions, network messages, account posting, status communication and later reconciliation. This guide describes a simplified lifecycle for education. It does not promise that every transaction succeeds instantly, explain every product variant or make a payment-network partnership claim for Centaur Careers.
Participants and basic payment concepts
A UPI transaction can involve the payer, the payer's app or payment service provider, the payer bank, NPCI's system, the beneficiary bank and the payee or merchant. The exact participants and message path depend on the transaction type and participant arrangement. A virtual payment address can help address a transaction without the payer manually entering account details, while an account-and-IFSC flow uses different identifiers. Some services and product options vary by app and bank. Consult NPCI and the relevant bank for current supported methods, limits, protections and complaint routes.
- Payer: initiates a payment and authorizes it through the supported journey.
- App or PSP: presents the interface and routes the customer's instruction according to its role.
- Payer bank: validates and processes the debit request under its controls.
- NPCI and participating systems: exchange and route payment messages under the scheme rules.
- Beneficiary bank and payee: receive the credit-side instruction and reflect the result through their systems.
Step 1: initiation and instruction validation
A customer selects a payee or enters an approved payment identifier, amount and optional description. The app displays the information available for confirmation, and the payer should verify the recipient and amount before authorizing. The service validates whether the request is well-formed and whether the payer is enrolled and connected as required. Invalid identifiers, unavailable services, device or network problems and user mistakes can interrupt the journey before a payment is completed. A displayed screen is not always the final proof of the ledger outcome; transaction references and official status should be retained.
Step 2: authentication and authorization
The payer authorizes the transaction using the supported authentication method. NPCI's customer FAQ describes a UPI PIN as a credential used to authorize bank transactions and warns users not to share it. An operations professional should never ask a customer to disclose a PIN or one-time credential. The payer bank applies its authentication and risk controls and returns a response through the transaction path. Specific limits, product features and user journeys may differ and can change; check current NPCI and bank guidance.
Step 3: routing, debit and beneficiary-side processing
After authorization, messages are routed among participating systems and banks under the scheme's technical and operating rules. The payer bank processes the debit request and the beneficiary-side institution processes the credit instruction. Status messages then return to the app and relevant participant systems. This explanation is deliberately conceptual: message order, retry logic, timeouts, reversals, settlement and dispute handling depend on the scheme version, transaction type and participant rulebook. Do not treat this paragraph as a system design specification or use it to troubleshoot a live payment.
- Customer confirms payee and amount in the supported app.
- The request is authenticated under the payment and bank controls.
- Participating systems route the instruction and exchange status messages.
- Banks process the relevant debit and credit-side events under their procedures.
- The app and bank records expose a status and reference for later checking or support.
Success, pending and failed transactions
A transaction can be reported as successful, declined, pending or in another state defined by the bank or app. If a customer sees a debit without the expected confirmation, they should use the official transaction history and bank or app support route, preserve the reference and follow the current dispute process. The same screen may not reveal whether a downstream record has reconciled. Operations staff compare source references, timestamps, amount, payer and beneficiary-side status in authorized systems. They should avoid promising a reversal or credit before an authoritative record confirms it.
Declined transactions and delayed status updates can have different causes, including insufficient funds, authentication error, participant downtime, technical timeouts, incorrect details or temporary network issues. The cause should be verified rather than guessed from a generic error message. Current official NPCI and bank guidance describes the available customer steps; timelines and escalation channels can vary. Never ask a customer to repeat a payment solely because a first status is unclear without checking the applicable process, since duplicate payments can create additional issues.
Reconciliation and controls behind the customer screen
Payment operations teams may compare transaction messages, bank postings, settlement files, participant reports and customer-facing status records. A reconciliation uses defined references and rules to identify completed, missing, duplicate or inconsistent records. Exceptions should be assigned, aged and escalated with evidence. Access to payment information is restricted, and credentials must remain secret. Controls can include authentication, transaction limits under current product rules, duplicate detection, secure message exchange, incident response, reconciliation and customer grievance handling. The exact controls belong to participants and their approved scheme and regulatory framework.
- Retain the transaction reference, date, amount, status and source used for investigation.
- Distinguish user-interface status from bank posting and settlement evidence.
- Detect duplicates and investigate timeout or reversal records under approved rules.
- Protect credentials and never ask a customer to reveal a UPI PIN.
- Route complaints through the current official bank, app or scheme channel.
Fictional exception example
Suppose a fictional customer shows an app screen marked pending and a bank notification showing a debit, while the merchant system has no matching receipt. The operations analyst records the reference and timestamps, checks authorized payer-bank and beneficiary-side status records and compares them with the approved exception procedure. If one source is unavailable, the case remains unresolved and receives an owner. The analyst does not mark the transaction successful based on the debit alone or tell the customer to pay again without guidance. The scenario is invented and does not state a universal reversal timeframe.
Career relevance in digital payments operations
Payment operations roles can involve transaction monitoring, customer issue triage, reconciliation, settlement support, merchant operations, service availability and incident coordination. A useful learner project can create a fictional transaction file with success, decline, duplicate and pending statuses, then design a reconciliation view and neutral escalation notes. Label every record as synthetic and do not use real UPI identifiers, phone numbers, QR codes or customer screenshots. Current employer requirements vary; one article does not promise access to a payment network or a particular job.
Reversals, disputes and safe customer support
A reversal, refund, dispute and complaint are related customer-service terms but they are not interchangeable. A reversal concerns an earlier payment event that did not complete as intended under the applicable process; a refund is generally a new return-of-funds event initiated through an authorized path; a dispute is a request to investigate or challenge an outcome; and a complaint may concern service or handling. The exact definitions and steps depend on the transaction and current bank or scheme rules. An operations employee should use the correct case type and avoid promising an outcome before the authorized record confirms it.
A support case should capture the transaction reference, payer and beneficiary context permitted for the role, amount, time, displayed status and source records reviewed. The analyst checks whether a duplicate debit, delayed confirmation or incorrect recipient may be involved, but does not ask for a UPI PIN or one-time credential. If evidence is inconsistent, preserve both sides and follow the bank's escalation path. Customers should rely on the official app, bank or scheme contact details rather than phone numbers or links sent by an unknown person.
Fraud-awareness communication should be simple and specific. A customer should not approve a collect request or scan a code unless they understand who will receive the payment and why. A QR code is not proof of a refund, and a person receiving an incoming payment does not need to disclose a PIN to collect it. Current NPCI and bank guidance should be checked because product features and safety notices evolve. This article cannot assess a customer's individual transaction or confirm that a particular message is genuine.
Payment operations and reconciliation signals
At scale, payment teams reconcile event messages with account postings and merchant or beneficiary records. They may track success, decline, pending, reversal, duplicate and timeout populations, but definitions need to be consistent across participants. A sudden change in pending rates may reflect a participant incident, app release, connectivity issue or data mapping problem. Operations reports should identify the measurement window and source, and incident owners should coordinate through approved channels. A status dashboard is useful for triage but does not replace transaction-level evidence when resolving a customer case.
- Store only the identifiers needed for the authorized case and protect them from exposure.
- Compare participant status and ledger evidence before marking a case resolved.
- Separate a payment reversal from a merchant refund or a customer complaint.
- Use current complaint and escalation routes; do not promise a universal resolution time.
- Report recurring technical patterns to the incident owner with a defined data period.
Frequently asked questions
What is the UPI payment lifecycle?
At a high level, a customer initiates and authorizes a request, participating systems route it, banks process relevant account events, a status is returned and records are reconciled. Exact flows vary by transaction and participant.
Does UPI work 24/7?
NPCI's public customer FAQ describes UPI payments as available around the clock, but an individual transaction can still be affected by participant availability, maintenance or technical issues. Check current official service notices.
What should I do if a UPI payment is pending?
Check the official transaction history, keep the reference and use your bank or app's current support and dispute instructions. Do not share your PIN or rely on an unverified contact.
Can a UPI PIN be shared with support staff?
No. NPCI advises customers not to share the UPI PIN. Use official support channels and never disclose credentials.
Read NPCI's UPI frequently asked questions
Review NPCI's UPI product statistics
Explore the Digital Payments module
Explore FinTech and Neo-Banking learning information
Read about digital payments operations careers
Read the digital payments operations career guide
Review the bank reconciliation process resource
Review RBI material on payment systems
Ask about current Digital Payments learning scope
Editorial note: reviewed 28 September 2026. UPI features, limits, scheme rules and complaint processes can change. Check current NPCI and bank instructions. This is educational and not financial advice.
Continue your finance career journey
Explore the learning tracks and placement support available through Centaur Careers.