
Finance Operations
Accrual vs Deferral Accounting: Examples and Controls
Compare accruals and deferrals with fictional examples, timing diagrams, journal-entry logic and the controls used during financial close.
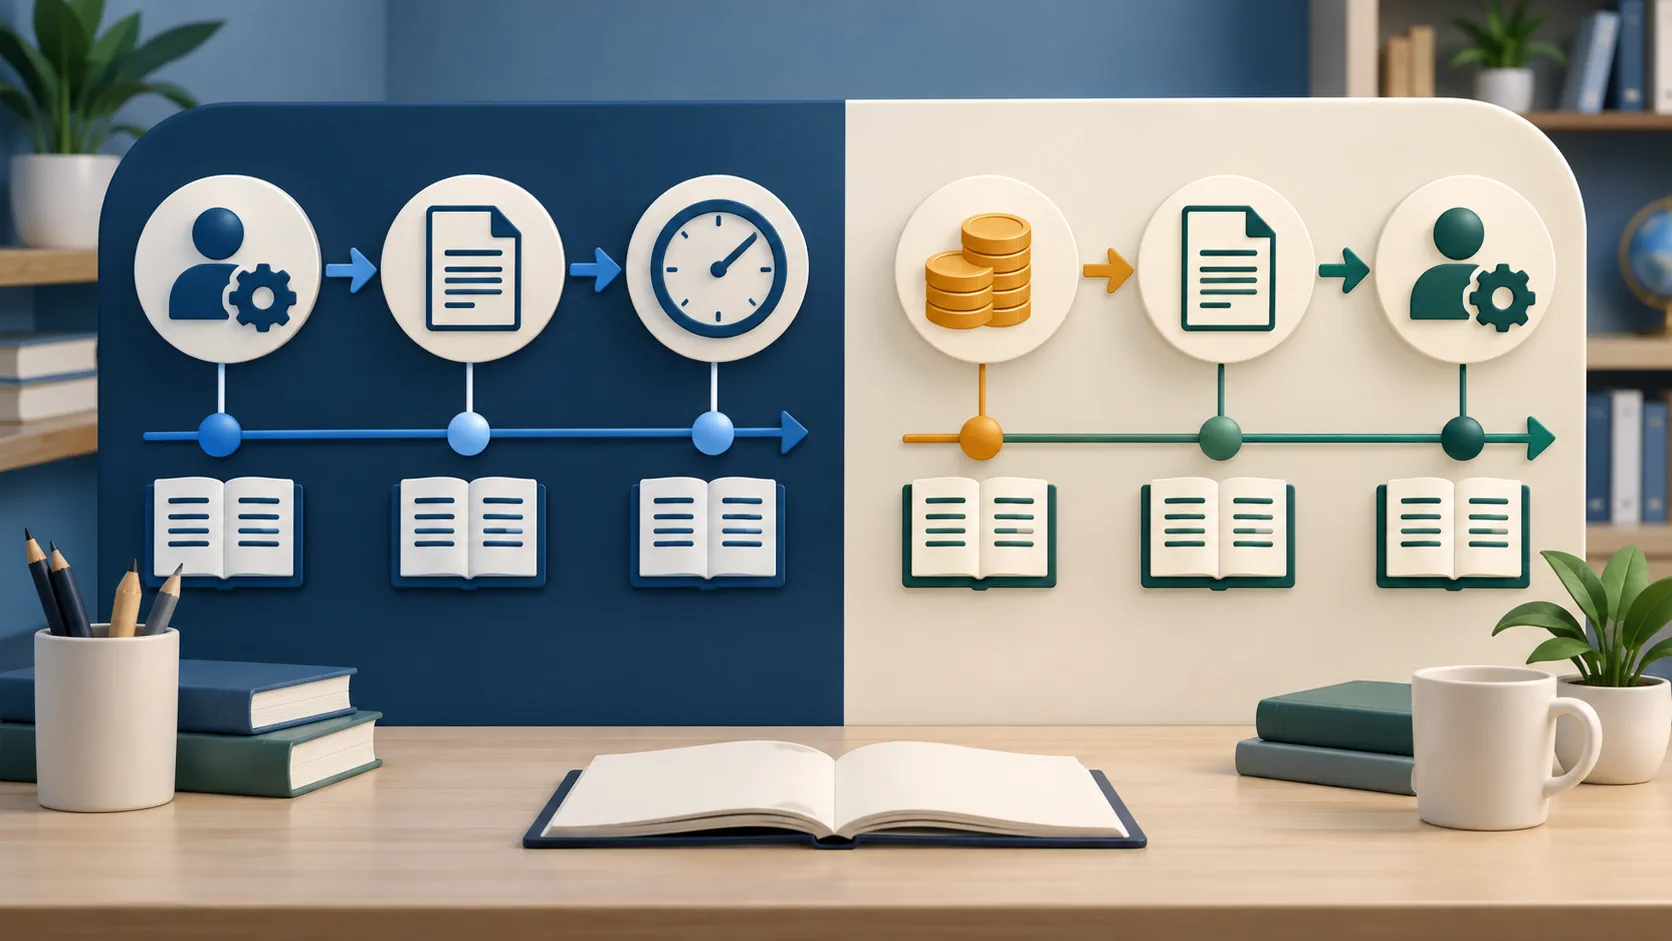
Accruals and deferrals are timing concepts used to place income or expense in the period to which it relates, subject to the applicable accounting framework and entity policy. An accrual generally recognises an amount before cash is received or paid when the underlying activity belongs to the period. A deferral generally postpones recognition after cash has already been received or paid because the related service or benefit belongs to a later period. This guide uses simple fictional examples for learning and does not prescribe a journal entry for a real entity.
Accrual versus deferral in one view
- Accrual: the economic activity is recorded for the period even though the invoice or cash event may occur later.
- Deferral: cash or an invoice is recorded first, while recognition is held for a later period as the service or benefit is delivered.
- Both: require evidence, a period basis, a documented calculation and review under the relevant policy.
- Neither: should be used as a plug to make a target balance or result look reasonable.
Fictional accrual example
A fictional company receives legal services during September, but the supplier invoice arrives in October. If the service belongs to September and the policy supports an estimate, the close team may record an accrual for the supported September amount and reverse or clear it when the invoice is processed. The preparer keeps the service evidence, calculation, period, assumptions and approval. The invoice later provides a comparison point, but it does not automatically prove that the original estimate was correct. All facts and amounts in this example are invented.
Fictional deferral example
A fictional customer pays for a twelve-month service before all of the service has been delivered. The receipt is recorded according to the organisation's process, while recognition is allocated to the periods that receive the service under the applicable policy. The schedule should show the start date, service period, amount, release pattern and reviewer. A deferral is not simply a delayed invoice; it is a timing decision supported by the nature of the underlying obligation or benefit.
Controls to check
- Identify the transaction, service period, contract or source evidence.
- Confirm the accounting basis and the policy owner responsible for the treatment.
- Calculate the amount with a reproducible method and record assumptions.
- Check whether a reversal, release or invoice-clearing step is needed.
- Compare estimates with later invoices or outcomes and investigate material differences.
- Obtain the required review and retain the approval and supporting evidence.
Common mistakes
Common mistakes include confusing cash timing with recognition, using a prior-period schedule without checking the service period, failing to reverse an accrual, releasing a deferral on the wrong date, and copying a calculation without current evidence. A spreadsheet can calculate a schedule, but it cannot decide whether the underlying policy applies or whether a source record is reliable. That judgment belongs within the approved accounting and review process.
Learn how financial accounting flows into statements
Review month-end close controls
Revise accounting principles and examples
A useful study exercise is to create a timeline with cash date, invoice date, service period, recognition date and reversal or release date. Then ask what evidence would change the conclusion. This approach is safer than memorising one journal entry because real treatment depends on the entity, contract, reporting basis and current policy. The article is general education and not accounting, audit, tax or legal advice.
Continue your finance career journey
Explore the learning tracks and placement support available through Centaur Careers.