
Finance Operations
Month-End Close Process: Finance Operations Checklist
Understand the month-end close process, including cut-off, reconciliations, accrual review, variance checks, sign-off and control evidence.
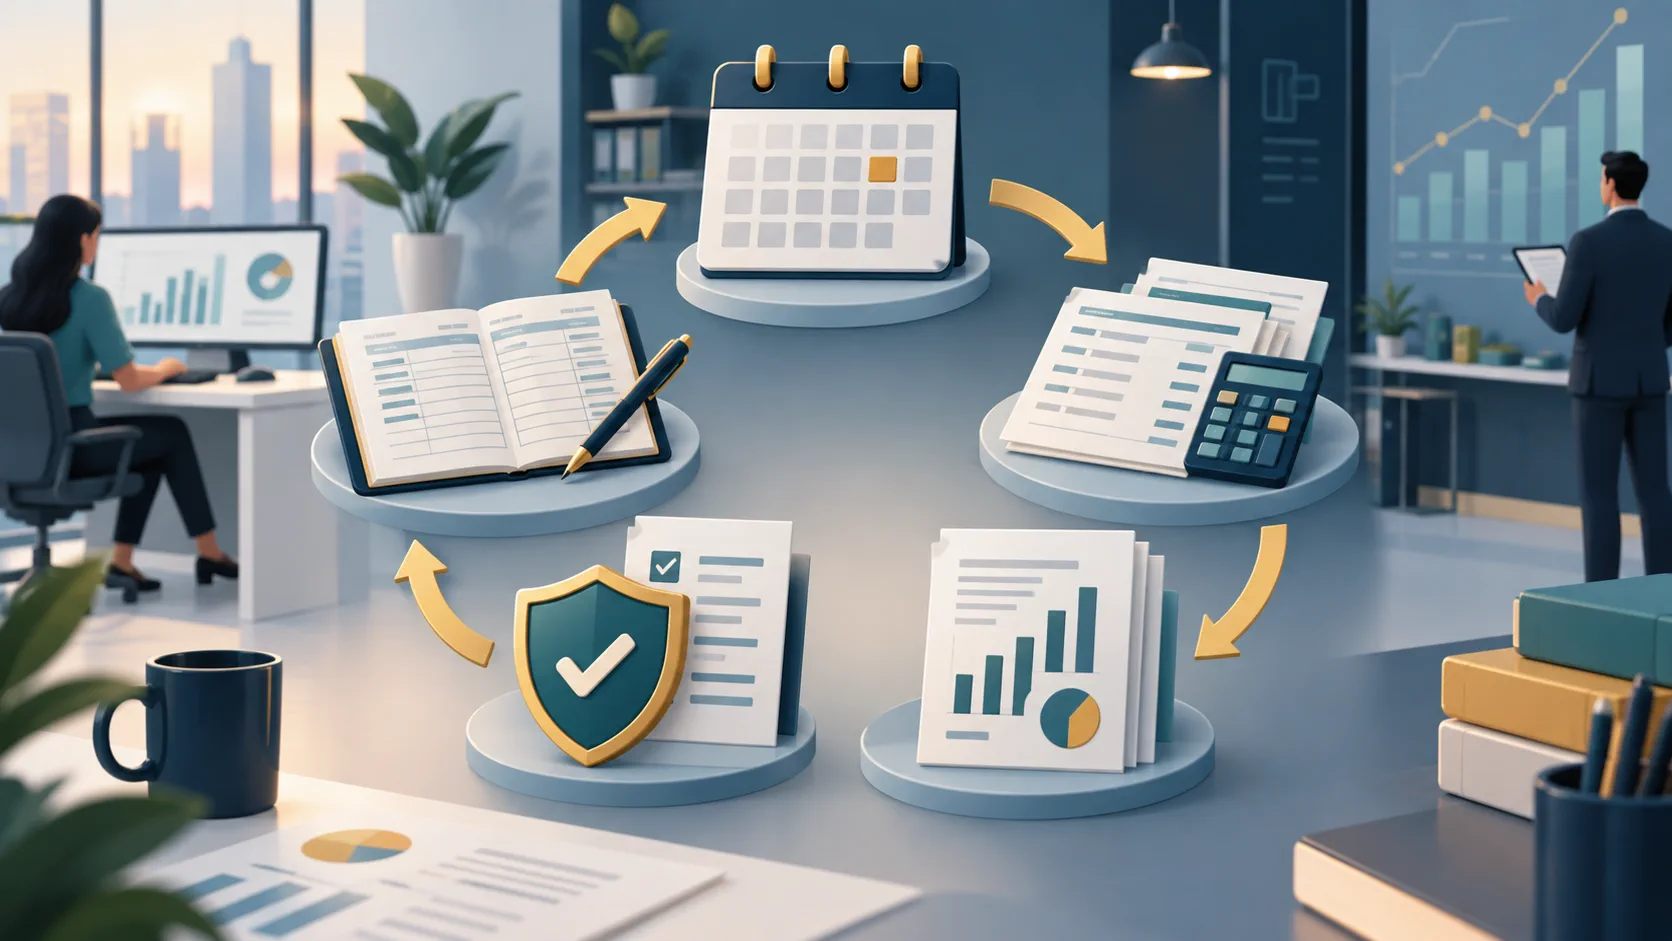
The month-end close process is the recurring set of finance activities used to complete a reporting period, reconcile important balances, review adjustments and produce an approved view of the period. A close is not simply a race to lock the ledger. It is a controlled sequence that turns source transactions into information that can be reviewed and explained. The exact close calendar, accounting basis, materiality approach and sign-off authority vary by organisation. This article is a practical learning guide and all examples are fictional.
What happens during a month-end close
A typical close starts with cut-off and source completeness, moves through routine posting and reconciliations, then reviews accruals, prepayments, estimates, intercompany items and unusual movements. The team prepares reports, performs analytical review, obtains approval and retains evidence. Some work begins before the last day of the month; other tasks depend on bank statements, payroll, supplier information or system feeds received afterward. A good calendar shows dependencies and owners instead of treating the entire close as one undifferentiated task.
A practical close checklist
- Confirm the reporting period, entity scope, reporting basis, cut-off and close timetable.
- Check that important operational feeds, invoices, receipts, payroll inputs and bank records are complete or clearly marked as pending.
- Post authorised routine entries and monitor rejected, duplicate or incomplete records.
- Reconcile bank, subledger, intercompany, suspense and other risk-relevant balances with evidence and ageing.
- Review accruals, prepayments, depreciation, provisions and other adjustments according to approved policy.
- Investigate significant variances and document the observed driver separately from an assumption.
- Obtain preparer, reviewer and approver evidence, release the report and retain the final version and correction path.
Why reconciliation is the centre of the close
A close becomes unreliable when a team posts entries without knowing whether the underlying population is complete. Reconciliation connects the ledger to bank, subledger, operational or external records. An exception should state what differs, why it may differ, what evidence was checked, who owns the next action and when it will be revisited. A recurring difference is not resolved by copying last month's note. Equally, speed is not a control objective when it is achieved by deleting unmatched items or booking unsupported adjustments.
A fictional close review
Consider a fictional service company whose accrued expense balance rises from 80,000 to 110,000. The change may be reasonable, but the reviewer asks what evidence supports it. The preparer compares the open purchase orders, invoices received after cut-off, service confirmations and prior-period reversals, then records the calculation and assumptions. The final note explains the supported movement and identifies any estimate that needs follow-up. The figures and business are invented. The example does not set a materiality threshold or tell a real entity how to book an entry.
Roles and evidence
- The preparer assembles source data, performs the calculation or reconciliation and explains the result.
- The reviewer checks period, policy, evidence, arithmetic, unusual movements and unresolved risks.
- The approver authorises the report or adjustment within delegated authority.
- The close owner manages dependencies, ageing, escalation and the final calendar status.
- The control owner maintains access, mapping, templates, retention and testing expectations.
How to make a close more reliable
A useful improvement starts with recurring failure points: late source files, manual mapping, repeated reconciling items, unclear ownership, rejected interfaces or review bottlenecks. Record the root cause and a testable action, such as a new population check, a documented handoff or an independent review step. Automation can reduce repetitive work, but it does not remove the need to monitor feeds, investigate exceptions and apply judgment. A close dashboard should distinguish prepared, under review, approved, blocked and carried-forward work.
Read the financial reporting process and controls guide
Review reconciliation steps in finance operations
Explore the finance operations career guide
For interview preparation, describe a close task using four parts: source, check, exception and evidence. This structure demonstrates process thinking without claiming that one company's calendar applies everywhere. Centaur Careers publishes this article for education; it is not accounting, audit, tax or legal advice, and it does not promise a reporting result or employment outcome.
Continue your finance career journey
Explore the learning tracks and placement support available through Centaur Careers.