
Finance Operations
Working Capital Cycle: Formula, Steps and Operations
Learn how inventory, receivables and payables move through the working capital cycle, with a fictional example and practical control questions.
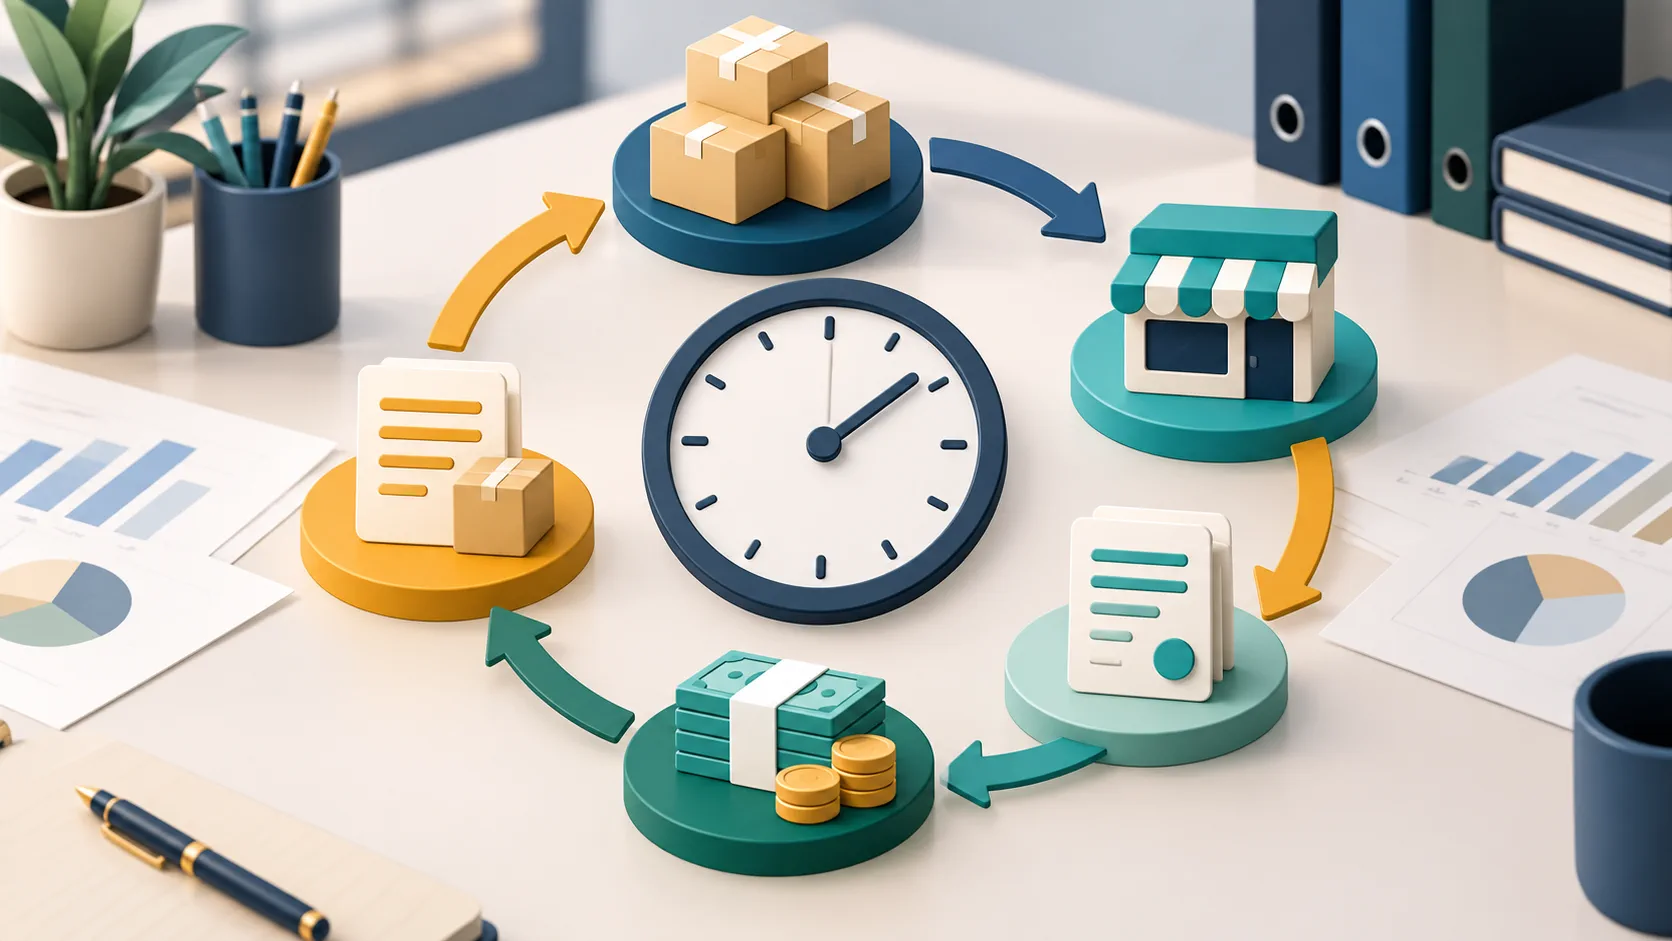
The working capital cycle describes how cash moves through day-to-day business operations: money is used to obtain inventory or services, sales create receivables, customers pay, and the business settles its own obligations. The cycle helps learners connect accounting balances with operational activity. It is not a universal performance target or a recommendation to change a company's payment terms. The correct interpretation depends on industry, contract, seasonality, controls and the entity's financial policy. Examples in this article are fictional.
What is the working capital cycle?
Working capital is often discussed through current operating assets and liabilities. Inventory and receivables may tie up cash, while approved payables can provide a period before the business pays suppliers. The operating cycle follows the time from obtaining inputs to collecting customer cash. A cash conversion view then considers the time inventory and receivables remain outstanding, less the period of supplier credit. Analysts should use the exact definitions required by the report or employer rather than treating one formula as suitable for every decision.
A simple cycle formula
A commonly used learning formula is: cash conversion cycle equals days inventory outstanding plus days sales outstanding minus days payables outstanding. The first component describes how long stock or work remains before sale, the second describes collection time, and the third describes the supplier-payment period. The formula is a diagnostic lens, not a complete measure of liquidity or profitability. A longer period may reflect deliberate service levels or seasonality; a shorter period may result from pressure on suppliers or customers. Use comparable periods and explain the drivers.
Fictional example
Suppose a fictional distributor holds inventory for 42 days, collects invoices in 28 days and pays suppliers in 35 days. Its simplified cash conversion cycle is 42 plus 28 minus 35, or 35 days. This does not mean every transaction takes exactly 35 days. It is an average view that should be tested against ageing reports, stock movement, customer collections, supplier terms and unusual items. If a large receivable is overdue, the average can hide the risk, so an operations team should inspect the population as well as the headline number.
Operational checks behind the numbers
- Reconcile inventory or service-delivery records to the relevant ledger and investigate unexplained differences.
- Review receivable ageing, unapplied cash, credit notes, disputes and customer-reference quality.
- Check payable invoices, approved terms, blocked items and duplicate-payment controls.
- Separate timing differences from genuine collection, inventory or supplier-risk issues.
- Track owners, ageing and evidence for exceptions rather than improving an average by deleting difficult records.
How finance operations teams use the cycle
Finance operations teams often support the cycle through invoice processing, cash application, reconciliation, ageing review, reporting and exception management. They may not set commercial terms, but their data quality helps decision-makers understand what is happening. A strong analyst can trace a movement from source record to ledger, identify a break and explain what further evidence is needed. That practical connection is more useful for career preparation than memorising a target number without context.
Compare accounts receivable and accounts payable
Review financial-management decisions and controls
Explore finance operations roles and skills
For study, draw three lanes for inventory, customer cash and supplier payments, then mark where evidence, approvals and reconciliations occur. The exercise should make the operational dependencies visible. Centaur Careers publishes this guide for general education; it is not financial, investment, accounting or business advice and does not promise a specific cash outcome.
Continue your finance career journey
Explore the learning tracks and placement support available through Centaur Careers.