
Finance Operations
Procure-to-Pay Process: Steps, Controls and Exceptions
Follow the procure-to-pay process from purchase request to payment, reconciliation and exception handling with a practical finance-operations checklist.
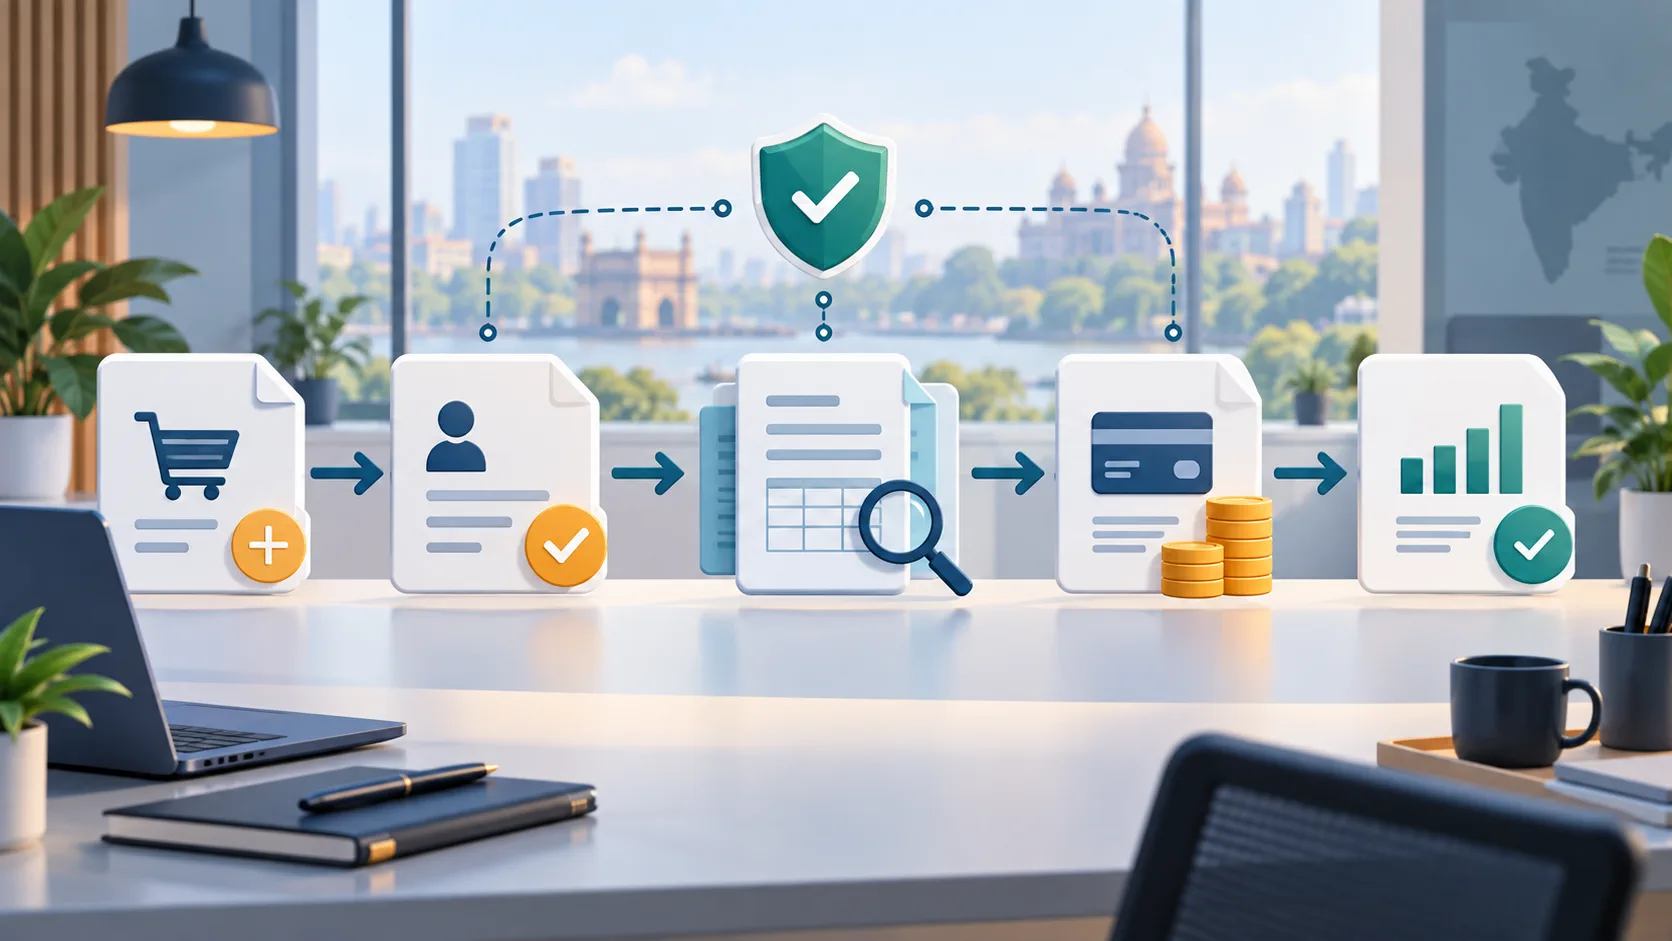
The procure-to-pay process is the controlled journey from a business need to an approved purchase, supplier invoice, payment and reconciled record. In a finance operations team, it connects procurement, the requesting department, accounts payable, the bank and the general ledger. The exact approval limits, tax treatment, systems and payment rules vary by organisation. This guide explains the workflow for learning and interview preparation; it does not replace an employer's policy, accounting framework or tax advice. All examples and amounts are fictional.
What procure to pay means
Procure to pay, often shortened to P2P, begins when an authorised team identifies a need and ends when the supplier has been paid and the transaction is recorded and reconciled. A complete process has more than an invoice. It should show who requested the purchase, who approved it, what was received, whether the invoice matches the evidence, who released the payment and how the entry was posted. Separating these stages reduces the risk of paying an unauthorised, duplicate or unsupported invoice.
The seven practical P2P steps
- Raise a purchase request that explains the business need, supplier context, amount, cost centre and required date.
- Review and approve the request under the organisation's delegated authority and budget process.
- Create or confirm the purchase order with the correct supplier, description, quantity, price, tax treatment and delivery details.
- Receive the goods or services and record evidence that the delivery or work was accepted by the authorised owner.
- Capture the supplier invoice and check its identity, reference, date, amount, tax fields, purchase order and receipt evidence.
- Approve and release the payment through the authorised bank or payment workflow, keeping a record of the approver and payment reference.
- Post the transaction, reconcile the payable and bank records, and close or escalate any exception rather than forcing the records to agree.
Three-way matching and its limits
Three-way matching compares the purchase order, receipt record and invoice. A match can support a routine approval, but it is not a universal guarantee that a payment is correct. Quantity, service quality, duplicate invoices, changed bank details, partial delivery and credit notes may still require human review. Service invoices can need a documented service-acceptance record rather than a warehouse receipt. A controlled exception explains what did not match, who owns the next check and what evidence permits an approved resolution.
A fictional invoice exception
Imagine a fictional invoice for 48,000 units of an approved currency while the purchase order shows 50,000 and the receiving record shows 47,500. The accounts-payable associate should not edit the invoice or accept the difference just to clear the queue. They record the three values, verify the delivery evidence, check whether a credit note or partial receipt exists, and route the case to the authorised procurement or business owner. The final action might be an approved adjustment, a corrected invoice or a rejection. The amount and case are invented.
Controls that protect the process
- Keep supplier creation and payment release separate where the organisation's control design requires it.
- Use duplicate checks across supplier, invoice number, amount, date and purchase order instead of relying on one field.
- Treat bank-detail changes as a controlled event with independent verification and a retained audit trail.
- Track blocked invoices by reason, owner, ageing and next action; do not delete unmatched items.
- Reconcile the accounts-payable subledger to the general ledger and payment account at the agreed frequency.
Why P2P matters for finance operations roles
P2P work develops evidence handling, data validation, accounting awareness, exception investigation and written communication. A process associate may spend one part of the day reviewing invoice fields, another part answering a buyer's query and another part documenting a payment break. Strong candidates can explain not only how to complete a task, but also how they know the source is reliable, what they would escalate and how they would prevent recurrence. These are transferable skills for finance operations and shared-services teams.
Revise accounting basics before working through P2P entries
Review the finance operations career guide
Explore the Finance Operations training module
For practice, draw the process with one owner and one evidence item for each step. Then add a duplicate invoice, a missing receipt and a bank-detail change to see where the workflow should stop. The correct response to an exception is a documented investigation and authorised decision, not a silent edit. This article is general education and does not promise a job, a payment outcome or a universal P2P policy.
Continue your finance career journey
Explore the learning tracks and placement support available through Centaur Careers.