
Finance Operations
Maker-Checker Controls in Banking Operations
Learn how maker-checker controls separate preparation, review and approval, with a fictional banking case and audit-evidence checklist.
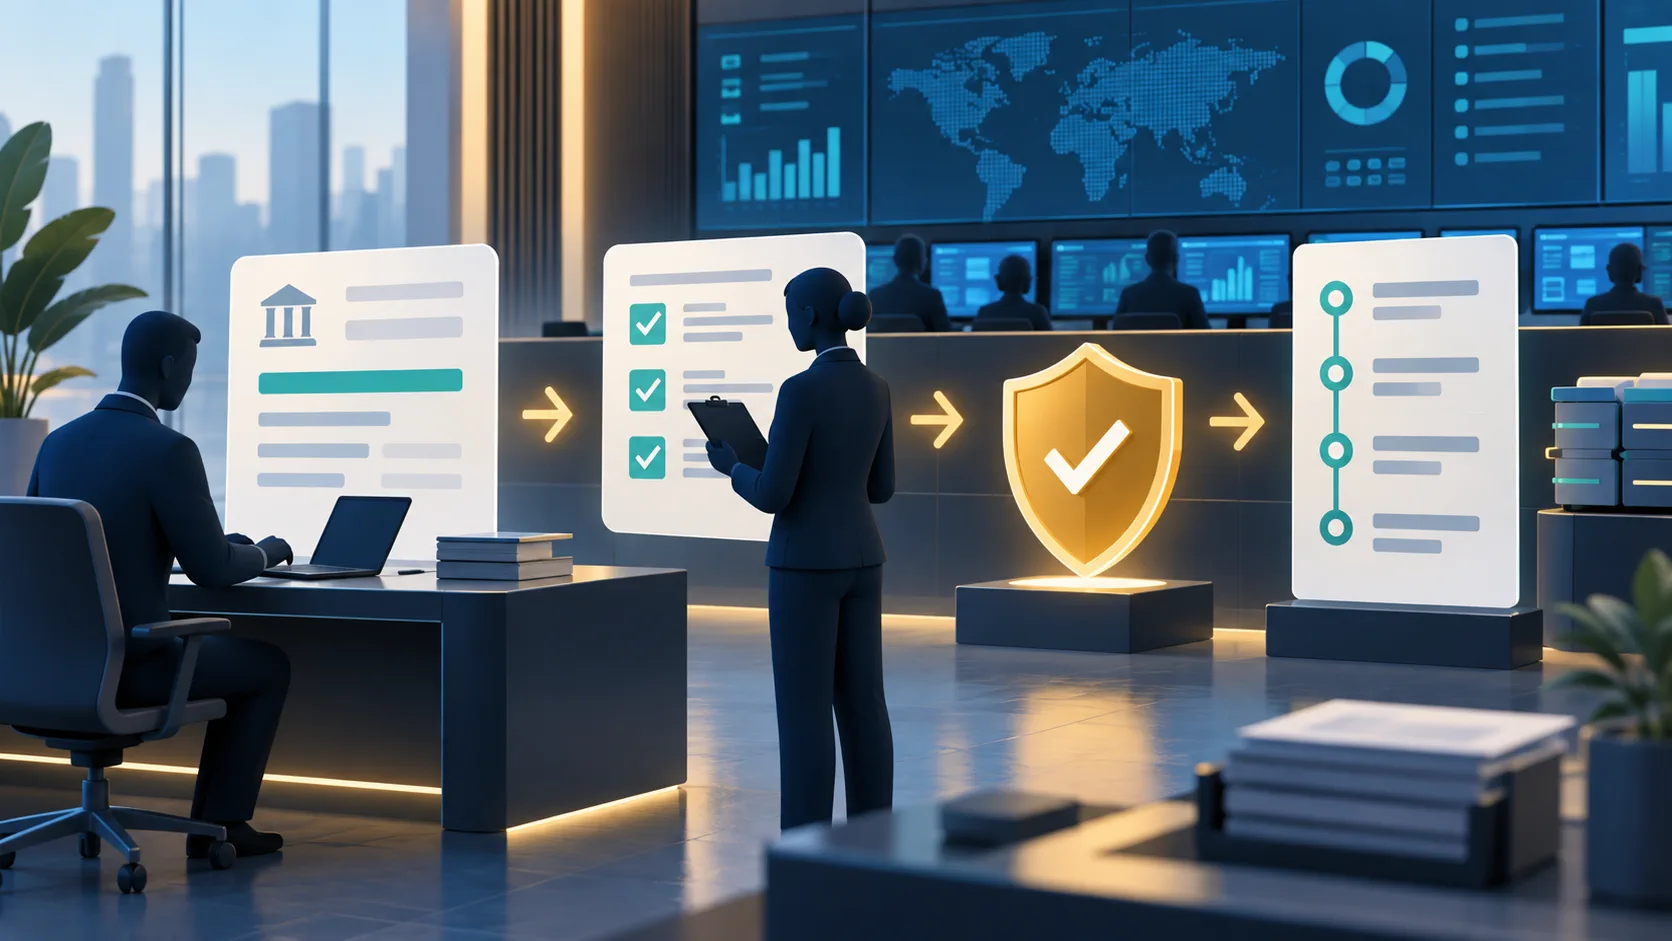
A maker-checker control separates the person or process that prepares an action from the independent person or process that reviews or approves it. In banking and finance operations, the arrangement can reduce errors, unauthorised changes and incomplete evidence, but it is not a magic label. The control must be designed for the risk, system, authority and staffing model. This guide explains the concept through a fictional workflow and should not be treated as a universal bank policy or audit conclusion.
Maker, checker and approver
The maker prepares a transaction, record, case or change using the approved source and procedure. The checker independently examines the fields, evidence, calculation, authority and outcome before the action proceeds. In some workflows, an approver is a separate role with delegated authority; in others, the checker may approve within defined limits. The important point is that the reviewer does not simply click through the maker's work without performing a meaningful check.
A fictional payment case
A fictional operations associate prepares a payment file after matching the beneficiary records, total amount and approved request. The checker independently compares the file to the request, reviews any changed details, confirms the batch total and records the review result. A mismatch in one beneficiary account is returned to the maker for evidence and correction. The checker does not silently edit the file, and the maker does not approve their own correction. The people, file and amount are invented.
What a meaningful check covers
- Completeness: the full population, batch or case is present.
- Accuracy: fields, amounts, references, dates and mappings agree with the source.
- Authority: the requester, approver, access and limit are valid for the action.
- Evidence: supporting records are current, legible, retained and connected to the decision.
- Exceptions: overrides, breaks and unusual items are visible, explained and escalated.
- Audit trail: the system or record shows who prepared, reviewed, changed and approved the item.
Limitations and control failures
A maker-checker arrangement can fail when users share credentials, when the checker is not independent, when the review is performed after release, when the system allows an unlogged override, or when the reviewer only checks a total without testing the population. A small team may need a documented compensating control, such as management review or a restricted release queue. The design should be tested against actual risk and system behaviour rather than assumed from a workflow name.
Testing whether the control operates
A control description says what should happen; an operating test checks what did happen for a defined sample or case population. The reviewer may inspect whether the maker and checker were different authorised users, whether the check occurred before release, whether the evidence covered the important fields, and whether exceptions were resolved under policy. A control can exist on paper and still fail when a user shares access, a queue is auto-approved or a correction is not linked to the original record. Testing should be designed by the responsible control owner or assurance team.
- Define the population, period and risk addressed.
- Inspect the system evidence and user roles.
- Check the timing of preparation, review and release.
- Record exceptions without changing the sample.
- Escalate a repeated failure to the process owner.
Study risk management in banking
Review reconciliation controls and exception handling
Explore finance operations roles
For an interview answer, describe the action, evidence, independent check, exception route and retained result. Do not claim that maker-checker alone prevents fraud or guarantees accuracy. Centaur Careers publishes this article for education; it is not a control certification, audit opinion, banking policy or employment promise.
Continue your finance career journey
Explore the learning tracks and placement support available through Centaur Careers.