
Retail Banking
Enhanced Due Diligence (EDD): A KYC/AML Workflow
Understand enhanced due diligence, how it differs from ordinary CDD, and how analysts document evidence and escalate a fictional review.
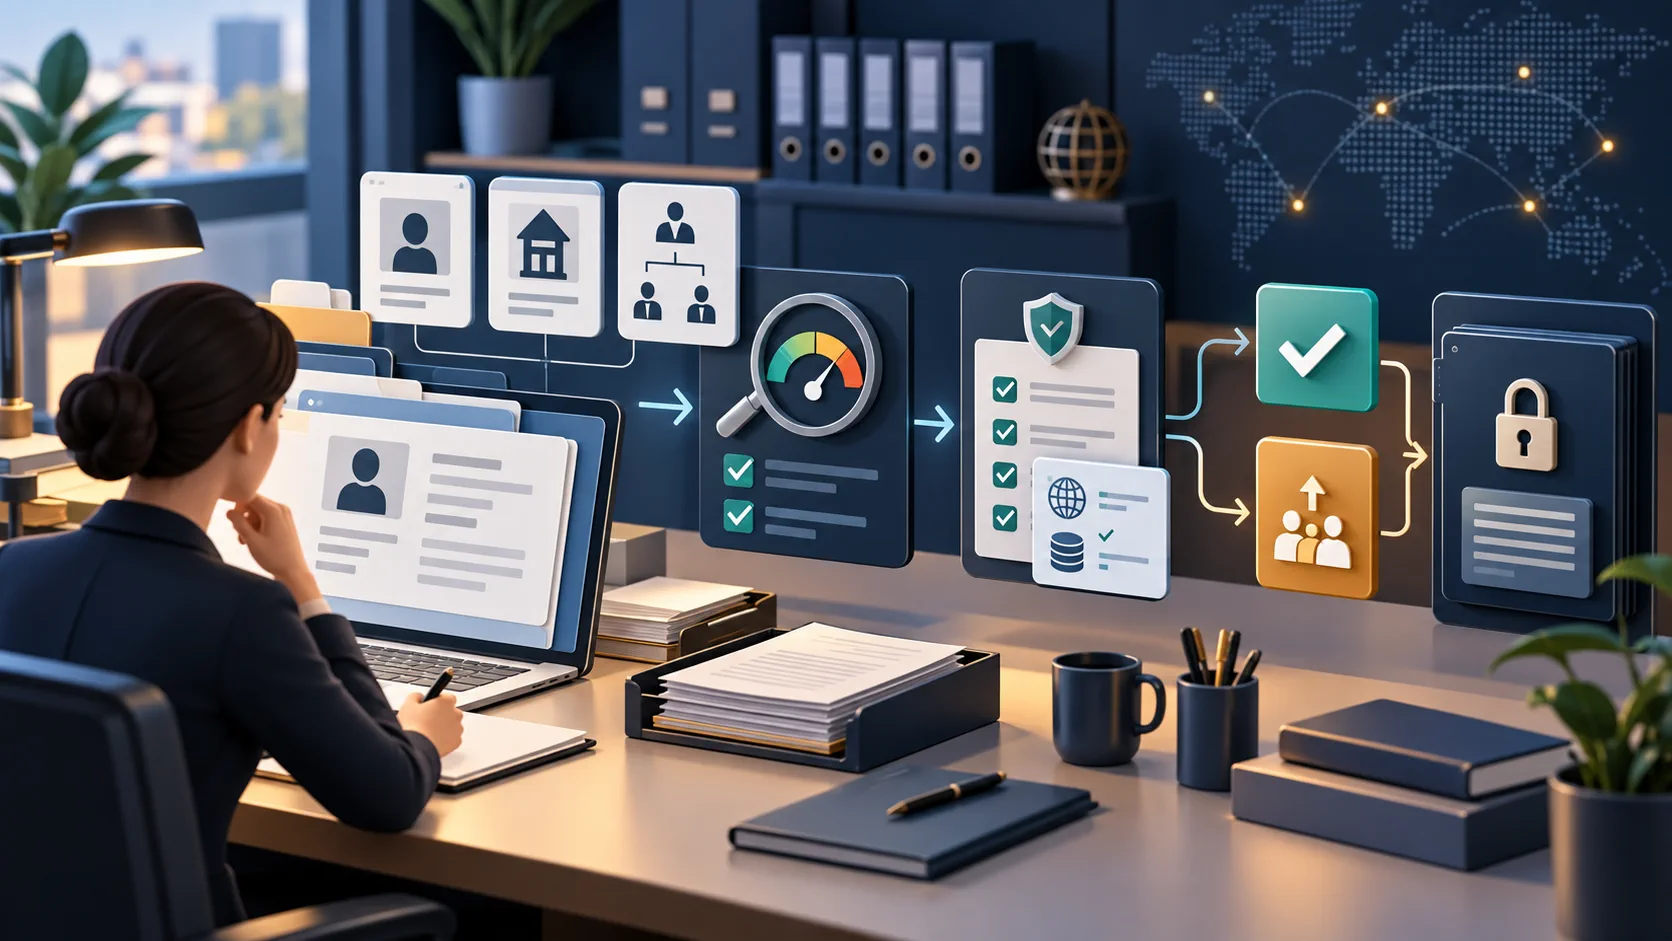
Enhanced due diligence, or EDD, describes additional customer or relationship checks applied when the approved risk-based process requires more information, scrutiny or approval than ordinary customer due diligence. The exact triggers, evidence and decision rights depend on jurisdiction, regulated entity, customer type, product and current policy. This guide explains the workflow for KYC/AML career learning without setting legal thresholds or giving evasion advice. Examples are fictional and should not be used to assess a real customer.
EDD versus ordinary due diligence
Customer due diligence establishes and understands the customer relationship using the applicable identification, ownership, purpose and monitoring process. Enhanced due diligence adds depth or senior review when risk or circumstances justify it. The difference is not simply a longer document list. EDD should have a documented reason, a defined evidence request, a responsible reviewer, a decision path and ongoing follow-up where required. A learner should always read the current internal procedure and regulator guidance rather than copying a generic online checklist.
A high-level EDD workflow
- Record the customer, relationship, alert or risk factor that triggered enhanced review.
- Confirm the scope, source and currency of the information requested under the approved procedure.
- Collect and protect permitted evidence about identity, ownership, purpose, activity and source information where relevant.
- Compare the evidence with the customer profile and record inconsistencies without silently changing the source.
- Escalate the case to the authorised compliance or management decision-maker when the procedure requires it.
- Document the decision, conditions, review date, monitoring or follow-up and any unresolved issue.
A fictional ownership review
A fictional business customer has a complex ownership structure that requires additional review under the organisation's procedure. The analyst maps the entities using approved records, notes which information is verified and which remains outstanding, and asks the authorised team how the relationship purpose should be documented. The analyst does not infer beneficial ownership from a web search or close the case because the customer supplied one document. The people, companies and records are invented.
Evidence and quality checks
- Use current, permitted and relevant source material with a recorded date.
- Separate verified facts, customer explanations, analyst observations and unresolved questions.
- Check consistency across identity, ownership, purpose, expected activity and transaction context where applicable.
- Protect data and share it only with authorised reviewers or systems.
- Record why a case was escalated, what decision was made and when it must be reviewed again.
Ongoing review and record quality
EDD does not always end when an initial decision is recorded. The approved process may require ongoing monitoring, periodic review, event-driven refresh or follow-up on an outstanding document. The analyst records what is known, what is still required, who owns the next action and when the case should return for review. A case note should make it possible for another authorised reviewer to understand the decision without relying on memory. If the customer profile changes, the risk assessment and evidence may need to be revisited under the current procedure.
- Use a clear case status such as open, pending evidence, escalated or closed.
- Keep dates and source versions with each important document.
- Do not treat an old approval as a permanent answer to a changed relationship.
- Protect sensitive information in training, exports and handoffs.
- Follow the current policy for retention, review and escalation.
Work through a fictional KYC onboarding case
Review KYC meaning, process and documents
Read AML controls and workflow
Explore the KYC and AML analyst career guide
For interview preparation, explain the trigger, evidence, inconsistency, escalation and follow-up without making a legal conclusion. Current rules and internal policy always control the live decision. Centaur Careers publishes this article for general education; it is not KYC, AML, legal, regulatory or customer-specific advice.
Continue your finance career journey
Explore the learning tracks and placement support available through Centaur Careers.