Finance Operations
Cost Accounting Methods: A Clear Worked Example
Learn cost accounting classifications and methods through a transparent fictional product example, including how allocation assumptions affect unit cost.
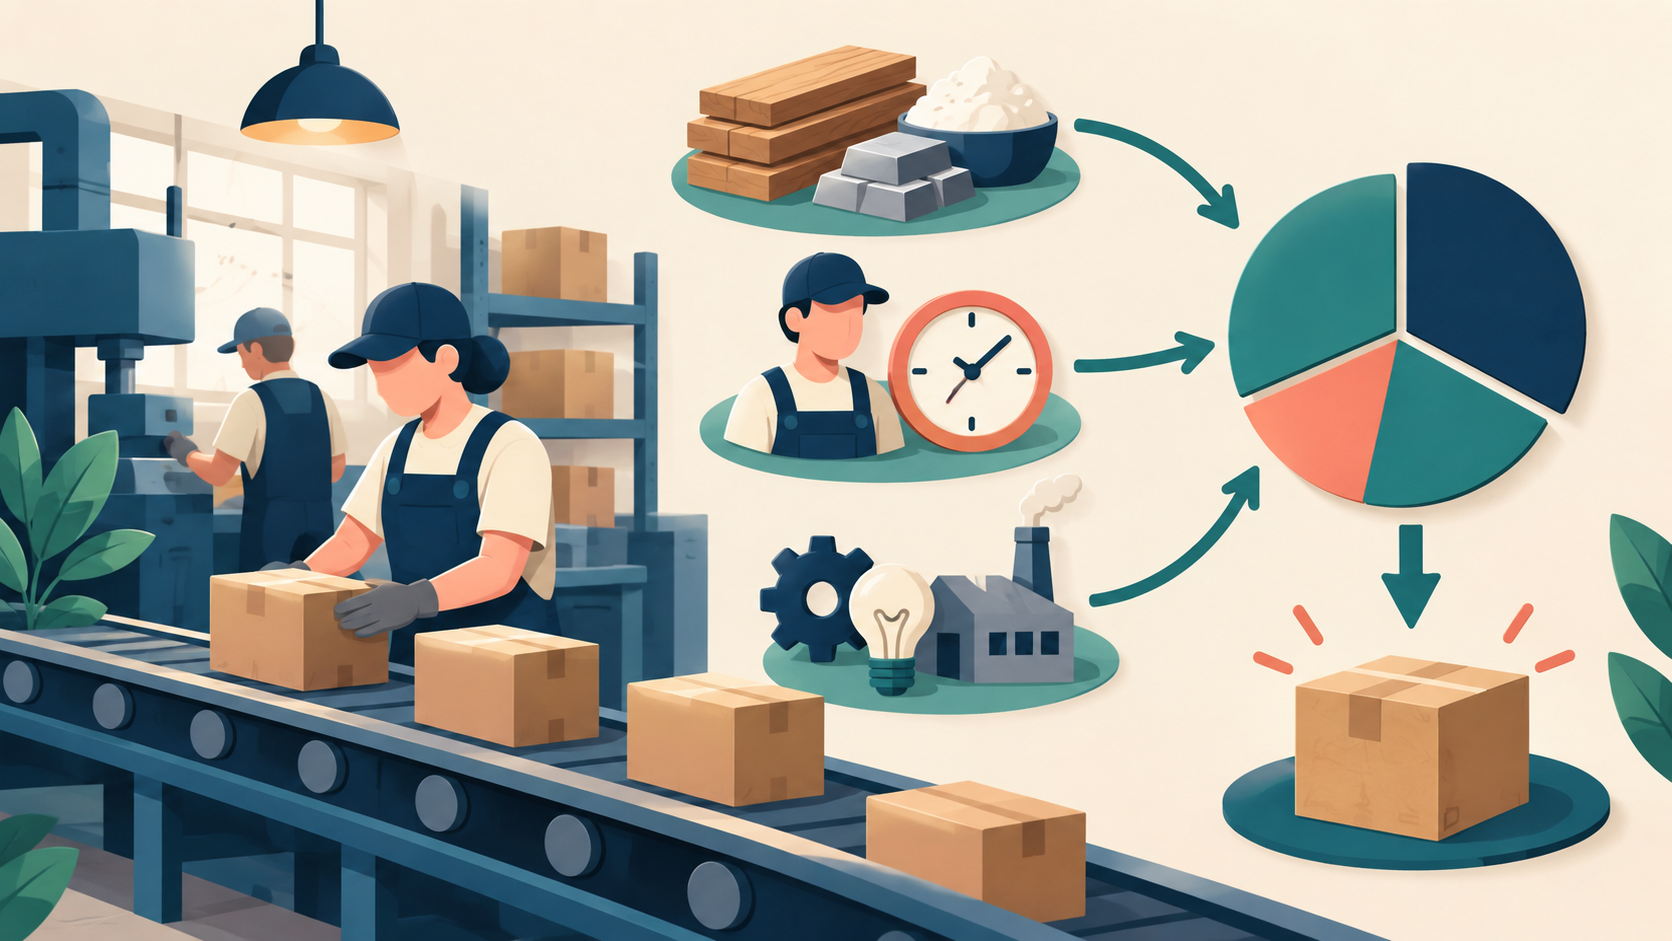
Cost accounting helps an organisation collect and analyse the costs of products, services, jobs or processes. In cost and management accounting, internal information can support planning and decisions, but the right method depends on what is being produced, how work flows and the organisation's approved accounting policy. The fictional example below shows cost allocation and basic cost classification; it is not a statutory valuation, a quote or a claim about Centaur Careers course coverage.
First distinguish the cost concepts
- Direct costs can be traced economically to a particular cost object, such as material used in a specific product batch.
- Indirect costs support more than one product, service or department and may need a justified allocation basis.
- Variable costs tend to change with an activity measure over a relevant range; fixed costs remain broadly stable in total over that range and time period.
- A cost object is the item being measured: for example, a product, service, project, customer segment or process.
- Job, batch, process and service costing are different approaches suited to different ways of delivering work; no single method fits every organisation.
A fictional unit-cost comparison
Suppose a fictional workshop makes 100 identical units in a month. Direct material is ₹20 per unit, or ₹2,000. Direct labour totals ₹1,000 and variable production overhead is ₹500. If the workshop allocates ₹1,500 of fixed production overhead to this batch, total illustrative production cost is ₹5,000, or ₹50 per unit. The direct material is traceable to the units; labour and overhead classification depends on the facts and the costing policy. The fixed overhead allocation is an assumption that must be documented, not a universal formula.
Now keep the same monthly fixed overhead and assume output rises to 120 units, while material, labour and variable overhead per unit remain unchanged. Variable costs total ₹4,200: ₹2,400 material, ₹1,200 labour and ₹600 variable overhead. Adding the same ₹1,500 fixed-overhead pool gives ₹5,700, or ₹47.50 per unit. This result is valid only under the stated simplified assumptions; changes in capacity, efficiency, product mix, waste, allocation basis or cost behaviour could change the analysis.
How to choose and check a costing method
- Define exactly what cost you need: a unit, job, batch, service or process.
- Identify source records and separate traceable costs from shared costs using the organisation's policy.
- Choose an allocation base that reasonably reflects how a shared cost is incurred, and state its limits.
- Reconcile the cost pool and quantities to source records, test a sample calculation and investigate unusual movements.
- Keep assumptions, exclusions, period and approval visible; do not present a classroom estimate as a quoted or audited cost.
Cost accounting and financial accounting are related but serve different purposes. Internal cost information can help managers understand resource use; published financial statements must follow the applicable reporting framework and entity requirements. A management decision may also need demand, quality, capacity, cash-flow and strategic information, not just an allocated unit cost.
Read the Institute of Cost Accountants of India study material
Review our accounting basics resource
Centaur Careers publishes this educational overview with a fictional example. It is not accounting or business advice, and it does not state that cost accounting is part of the current Financial Operations Masterclass curriculum. Verify current program scope on the program page before enrolling.
Continue your finance career journey
Explore the learning tracks and placement support available through Centaur Careers.