
Finance Operations
Cash Flow Statement: Direct vs Indirect Method
Compare the direct and indirect cash flow statement methods with a checked example and links to the balance sheet and income statement.
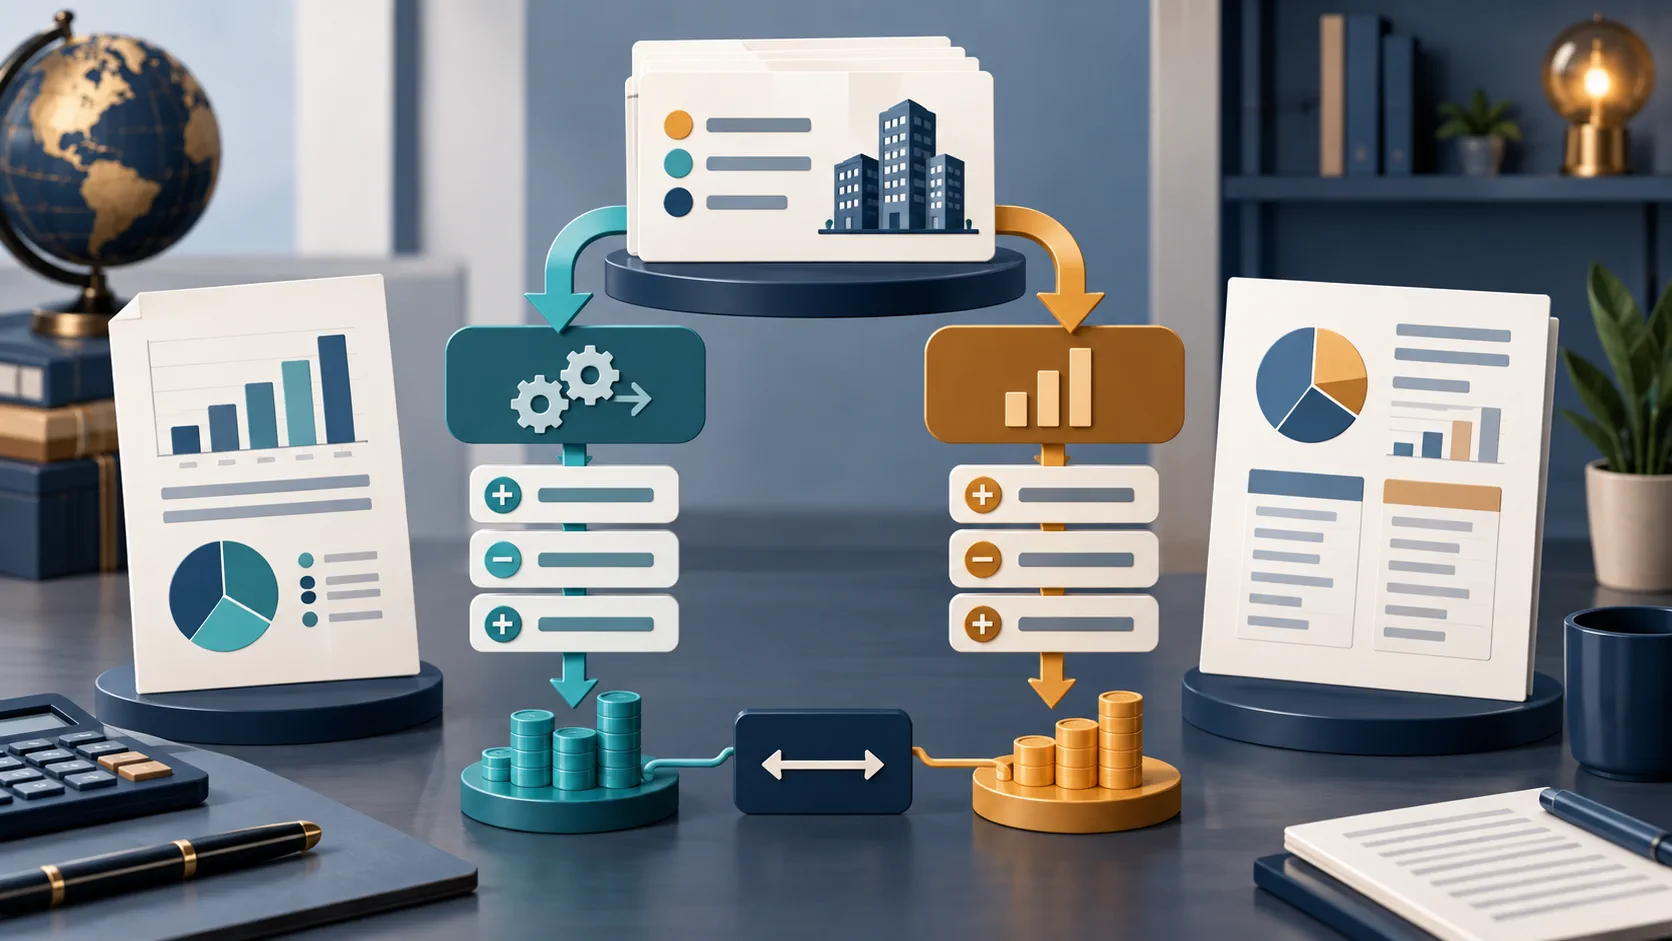
A cash flow statement explains how cash and cash equivalents changed during a period through operating, investing and financing activities. The direct and indirect methods mainly differ in how operating cash flows are presented. The direct method starts with cash receipts and cash payments, while the indirect method starts from a profit or loss measure and adjusts for non-cash items and changes in operating balances. The applicable reporting framework and entity policy determine the required presentation. The example below is fictional and designed to show the logic, not to prepare a real set of statements.
Direct method
The direct method presents operating cash activity in categories such as cash collected from customers, cash paid to suppliers and cash paid to employees. It is intuitive because the reader can see the major cash inflows and outflows. The finance team needs reliable cash classifications and source records. Bank data alone may not explain the business purpose of every movement, so the statement often depends on ledger mapping, payment references and controlled adjustments.
Indirect method
The indirect method begins with an accrual-based profit or loss figure and adjusts for non-cash items, non-operating items and changes in working-capital balances. Depreciation is added back because it is not a current-period cash payment, while an increase in receivables can reduce operating cash because revenue has been recognised without collection. The calculation should be tied back to the ledger and supporting schedules. A formula that balances but cannot be traced is not a reliable control.
A small fictional comparison
Assume a fictional business reports profit of 100,000. It has a non-cash depreciation expense of 12,000, an increase in receivables of 18,000 and an increase in payables of 7,000. A simplified indirect operating-cash calculation would start with 100,000, add back 12,000, subtract the receivables increase and add the payables increase, giving 101,000 before other items. A direct presentation would instead classify the actual customer collections and supplier or employee payments. The numbers are invented and omit many real reporting considerations.
Checks before publishing a cash flow statement
- Confirm the reporting period, entity boundary, currency and applicable reporting basis.
- Reconcile opening and closing cash to the relevant balance-sheet or cash records.
- Check that non-cash items are not presented as cash movements in the wrong section.
- Review working-capital movements against receivable, payable and inventory schedules.
- Document classification rules, mapping changes, unusual items and reviewer evidence.
- Keep the fictional or educational example separate from a real statutory or management statement.
How the two methods connect
The direct and indirect methods are different presentations of operating cash activity, not two different kinds of cash. Both should lead to the same operating cash result when prepared correctly under the applicable framework. This makes reconciliation important. A finance team can compare the direct cash categories to bank and ledger records, while the indirect method can be checked against profit, non-cash adjustments and working-capital schedules. If the results differ, the team investigates classification, cut-off, mapping or an omitted movement rather than choosing the more convenient answer.
- Can each cash category be traced to a source population?
- Are non-cash entries excluded from cash movement?
- Do working-capital changes agree with the related balance-sheet accounts?
- Are investing and financing movements separated consistently?
- Can a reviewer reproduce the bridge from source records to final statement?
Review the balance sheet equation with a worked example
Follow the financial accounting process
For interview preparation, explain why profit and cash are different and then trace one working-capital movement through the indirect method. The strongest answer distinguishes the presentation method from the underlying cash activity and acknowledges that current reporting requirements must be checked. Centaur Careers publishes this article for education; it is not accounting, audit, investment or tax advice.
Continue your finance career journey
Explore the learning tracks and placement support available through Centaur Careers.