Investment Banking
Bonds vs Equities: Difference and Operations Context
Compare bonds and equities by claim, income, risk, records and operations workflow, with a practical learner-friendly finance explanation.
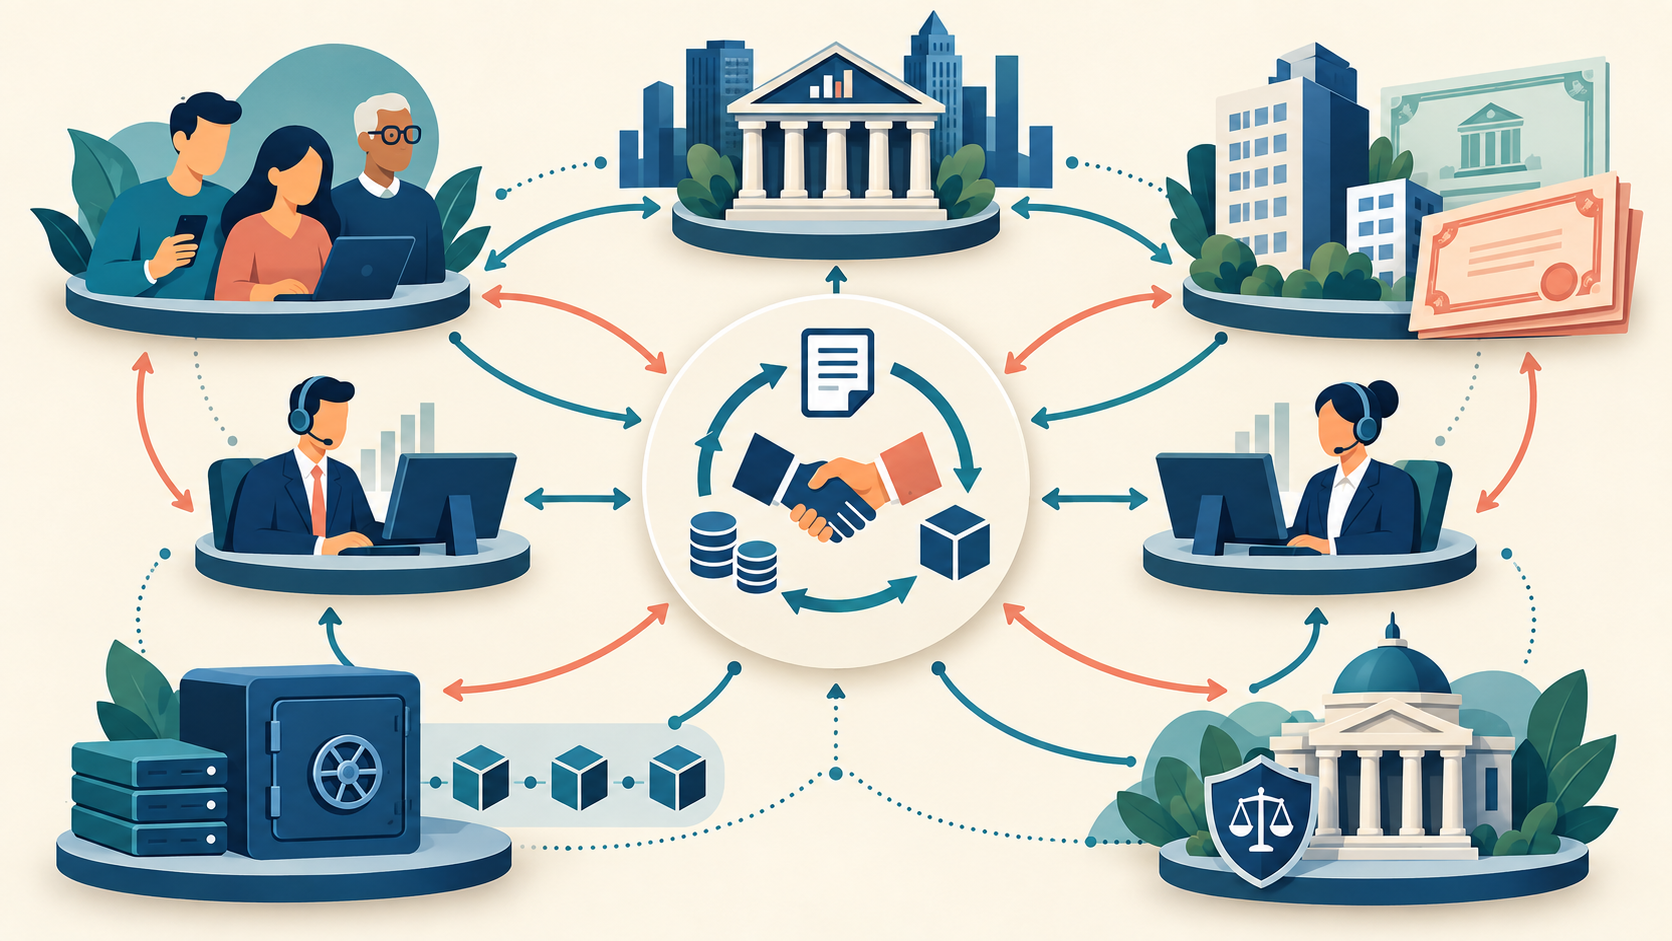
Bonds and equities are different financial instruments, even though both can appear in markets and securities operations workflows. A bond generally represents a debt claim with defined terms such as principal, maturity and interest or coupon features. An equity generally represents an ownership interest whose value and distributions depend on the company and market. The legal terms, risks, rights and processing details vary by instrument. This article is a learning comparison, not a trading recommendation or investment advice.
Bonds vs equities at a glance
- Claim: a bond is generally debt; an equity is generally an ownership interest.
- Cash flow: bonds may have contractual interest and principal terms; equity distributions are not the same contractual promise.
- Maturity: bonds commonly have a maturity or redemption structure; ordinary equity does not normally mature in the same way.
- Risk: both can lose value, but the drivers and priority of claims differ by instrument and situation.
- Operations: each needs accurate identifiers, quantity, price, settlement, income-event and position records.
How operations teams process the difference
An operations analyst does not need to make an investment decision to process a bond or equity record. They may validate instrument identifiers, trade terms, quantity, price, currency, settlement date, account, counterparty and event information. A bond workflow may also require attention to coupon, maturity or redemption events. An equity workflow may involve dividends, splits or other corporate actions. The exact fields and controls depend on the product and employer's systems.
Fictional workflow example
A fictional portfolio record shows 1,000 equity units, while an external statement shows 980. A separate notification mentions a corporate action. The analyst should not infer that the account is wrong from the quantity alone. They check the instrument, event date, effective date, transaction history, pending movement and statement scope, then document the evidence and escalate through the approved route. The same discipline applies to a bond income difference: identify the event, terms, expected amount and source before changing a record.
Questions to ask when learning the topic
- What claim or right does the instrument represent?
- Which terms drive cash flows, valuation or events?
- What source identifies the instrument and position?
- Which lifecycle step creates the operational record?
- What exception would require review before settlement or reporting?
Explore Investment Banking Operations training
Read the Investment Banking Operations career guide
Follow the trade lifecycle guide
Read the reconciliation resource
Browse all finance career insights
Review SEBI investor education material
Instrument definitions and current market rules should be checked against authoritative sources and the relevant product documentation. Centaur Careers provides this comparison for finance learning; it is not a recommendation to buy, sell or hold a security.
Continue your finance career journey
Explore the learning tracks and placement support available through Centaur Careers.